All Categories
Featured
There's no guarantee that you'll qualify to file, but declaring Chapter 7 bankruptcy might lead to having your financial obligations canceled, and a Chapter 13 personal bankruptcy might get you into a 3-5 year payment strategy to eliminate financial obligation. Here's what you should consider first:. Some debtors have no practical way to pay back all of their debt.
When you apply for insolvency, the court problems an automated stay, meaning that creditors will be barred from making collection attempts on your financial obligations through call and letters. Once you file, lenders will deal solely with your attorney and not you. When you file for bankruptcy your lenders need to stop all foreclosure and foreclosure procedures.
Personal bankruptcy is among the most harmful events for your credit, and it stays on your credit reports for 7-10 years after you file. This could imply being rejected new loans and credit in the near future. You'll have to pay for a lawyer, plus court filing fees, paralegal costs, insolvency trustee fees and costs for the required customer counseling.
Proven Strategies to Handle Debt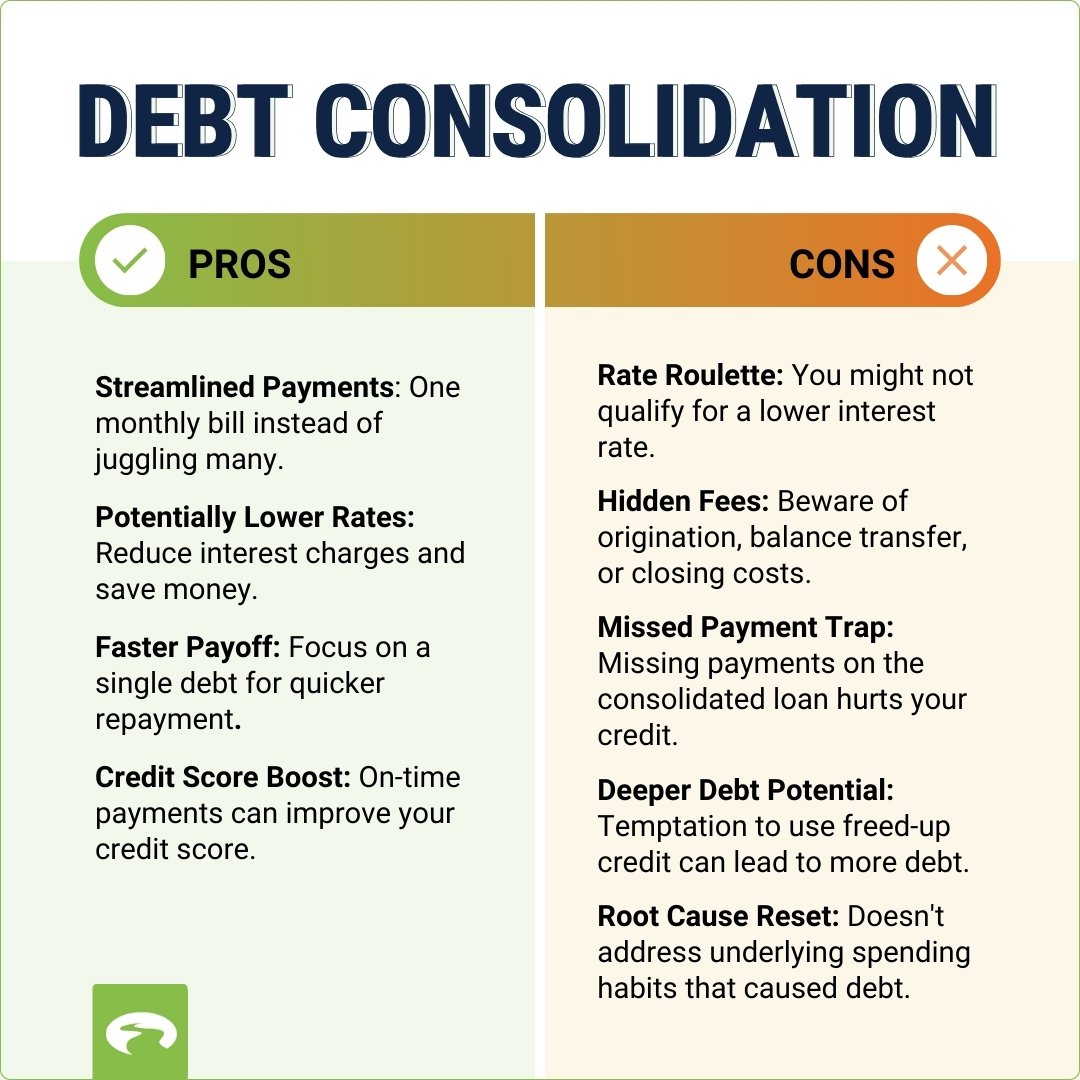
You don't need to work with a third-party to get debt-relief. Some alternatives for reducing debt could conserve you cash and assistance preserve your credit The finest option for you may even consist of a combination of Do it yourself options, spending plan tools or funding alternatives. Here are a few of the important things you can do on your own: Are you clear on where all your cash is going? If you don't keep track, there are probably a lots of costs you don't understand are setting you back.

Latest Posts
Will Debt Relief the Best Choice in 2026?
Cutting Household Debt with New Relief Programs
Expert Analysis Into 2026 Debt Consolidation Strategies