All Categories
Featured
Table of Contents
Here's a breakdown of a few of the most popular ones to consider: This strategy starts by listing your debts from tiniest to largest. Make minimum payments on all your cards while directing any additional funds towards the smallest balance. When you settle the tiniest financial obligation, you'll proceed to the next tiniest and get momentum with each success.
It takes longer to pay off high-interest financial obligations. Those focused on quick wins and staying inspired Focus on paying off the financial obligation with the greatest interest rate.
Those focused on reducing overall interest paid and quicker overall financial obligation decrease. This strategy combines your card debts into a single loan with a lower interest rate.
The application process is possibly faster than that of guaranteed loans. It needs good credit to certify, and interest rates are generally higher than those for secured loans. Those with excellent credit who prefer the simplicity of a single payment. A home equity loan usages your home's worth as collateral and can result in a lower interest rate.
This alternative may offer lower interest rates than charge card. Consolidating numerous financial obligations can likewise simplify monthly payments. Unsecured loans usually require great credit to certify. A home equity loan puts your home at risk if you stop working to pay back. This technique is ideal for people with good credit who prefer the simpleness of a single month-to-month loan payment.
How to Master Alabama Debt Negotiation Tactics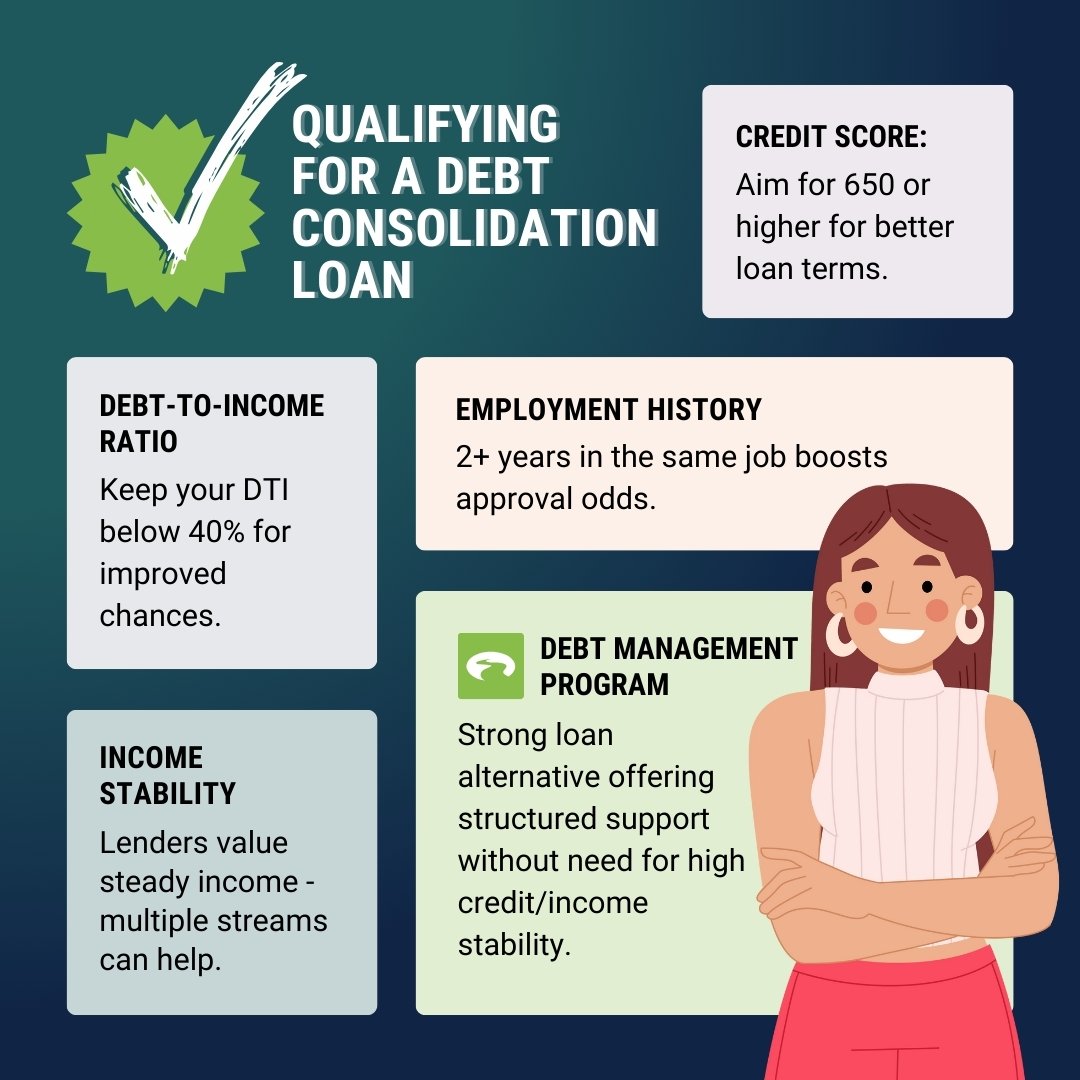
How to Negotiate Debt in 2026
Nevertheless, several other additional techniques can reduce credit card financial obligation stress: While the minimum payment keeps your account in great standing, it will not considerably reduce your debt. Paying even a little extra monthly will reduce the quantity you owe much faster. If possible, set up automatic payments above the minimum to make the process easier.
This can create a vicious cycle of debt that's hard to get away. Think about keeping a few cards locked away or briefly decreasing your credit limitations as you rebuild healthy costs routines. Creating an in-depth budget helps you track where your cash goes, revealing areas where you can cut back. This will maximize more funds to remove your financial obligation.
A credit therapy course can supply important guidance if you discover it tough to handle multiple credit cards properly. These courses use pointers and techniques for budgeting, debt reduction, and responsible credit use. Sticking to a debt management strategy can set you up for long-term financial success. If you're having a hard time, get in touch with the charge card issuer and explain your circumstance.
Wasatch Peaks Cooperative credit union provides confidential, no-cost, tailored financial obligation management counseling. These services can be important if managing financial obligation is frustrating or you require professional help developing a repayment technique. Among the fastest methods to deal with debt is to make more cash. Think about taking on a side gig, selling unused products, or asking for a raise at your current job.
You've paid off your credit cardnow what? Now that you have actually paid off your credit card, you may wonder about your next actions.
Seeking 2026 Financial Hardship Assistance
If you can pay your balance in complete monthly, search for a brand-new credit card that offers appealing rewards. Have a look at our helpful guide to identify the ideal variety of credit cards you need to have in your wallet. Even if you don't prepare on utilizing the card regularly, keeping it open for emergency expenses could be advantageous.
Just be conscious that it can momentarily reduce your credit report. Now that you have one less payment, there are a lot of ways to use that money to keep your monetary momentum going. You can use the funds to pay down other debts faster. For instance, you can redirect those payments towards your home loan or automobile loan payment.
Redirecting credit card payments to cost savings can supplement your funds for getaways, big purchases, or emergency funds. Credit bureaus monitor this metric to assess your credit use.
How to Get 2026 Financial Hardship Help
If you're having a hard time to stay within your spending plan, consider designating your credit card for emergency situations only. Understanding how long to pay off a credit card can help you make the needed lifestyle changes to reach your objective.
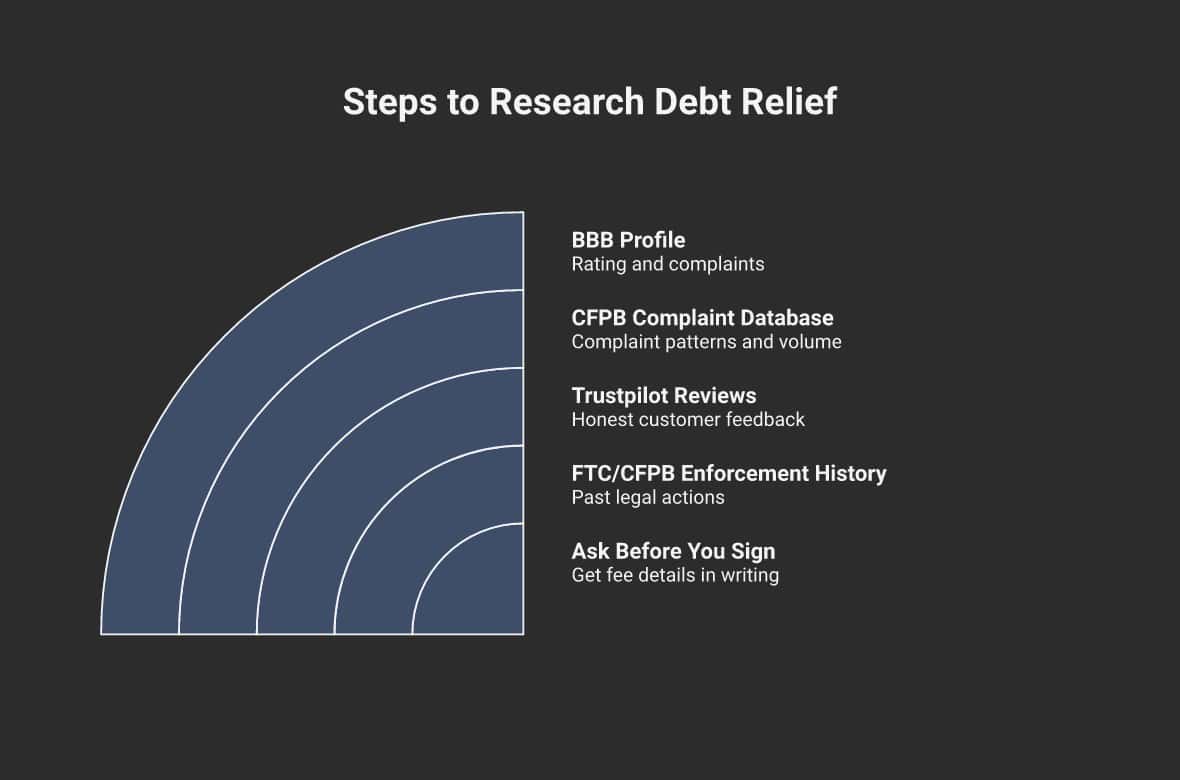
Analyze your costs practices and look for locations to cut down. Even little modifications in time can create room in your budget for debt payment. Be wary of services that assure to rapidly eliminate your debt or significantly settle it for a fraction of what you owe. These often turn out to be frauds.
When used properly, credit cards can substantially enhance your credit rating. Managing credit card financial obligation can be a substantial monetary challenge.

Devoting yourself to a method is the essential to getting out of credit card financial obligation quick. We can't make your month-to-month credit card payments for you (in fact, we kind of can with a personal loan), however we can show you how to get out of credit card debtfast!
If you have a $350 balance on a charge card with a 21-percent annual interest rate, and you make a minimum payment of just $20 monthly, it will take you 22 months to pay it off. That's nearly two years. If you double your payment to $40, you'll have the card settled in only 10 months.
Smart Debt Management for Struggling Families
This method becomes much more important when you use it to even bigger balances. State you are making the minimum $90 payment on a card with a $2,750 balance and a 21 percent interest rate: You'll find yourself making payments for the next 45 months (or 3.75 years). Yet, if you double the regular monthly payment, you'll run out financial obligation in only 18 months (1.5 years).

Latest Posts
Will Debt Relief the Best Choice in 2026?
Cutting Household Debt with New Relief Programs
Expert Analysis Into 2026 Debt Consolidation Strategies